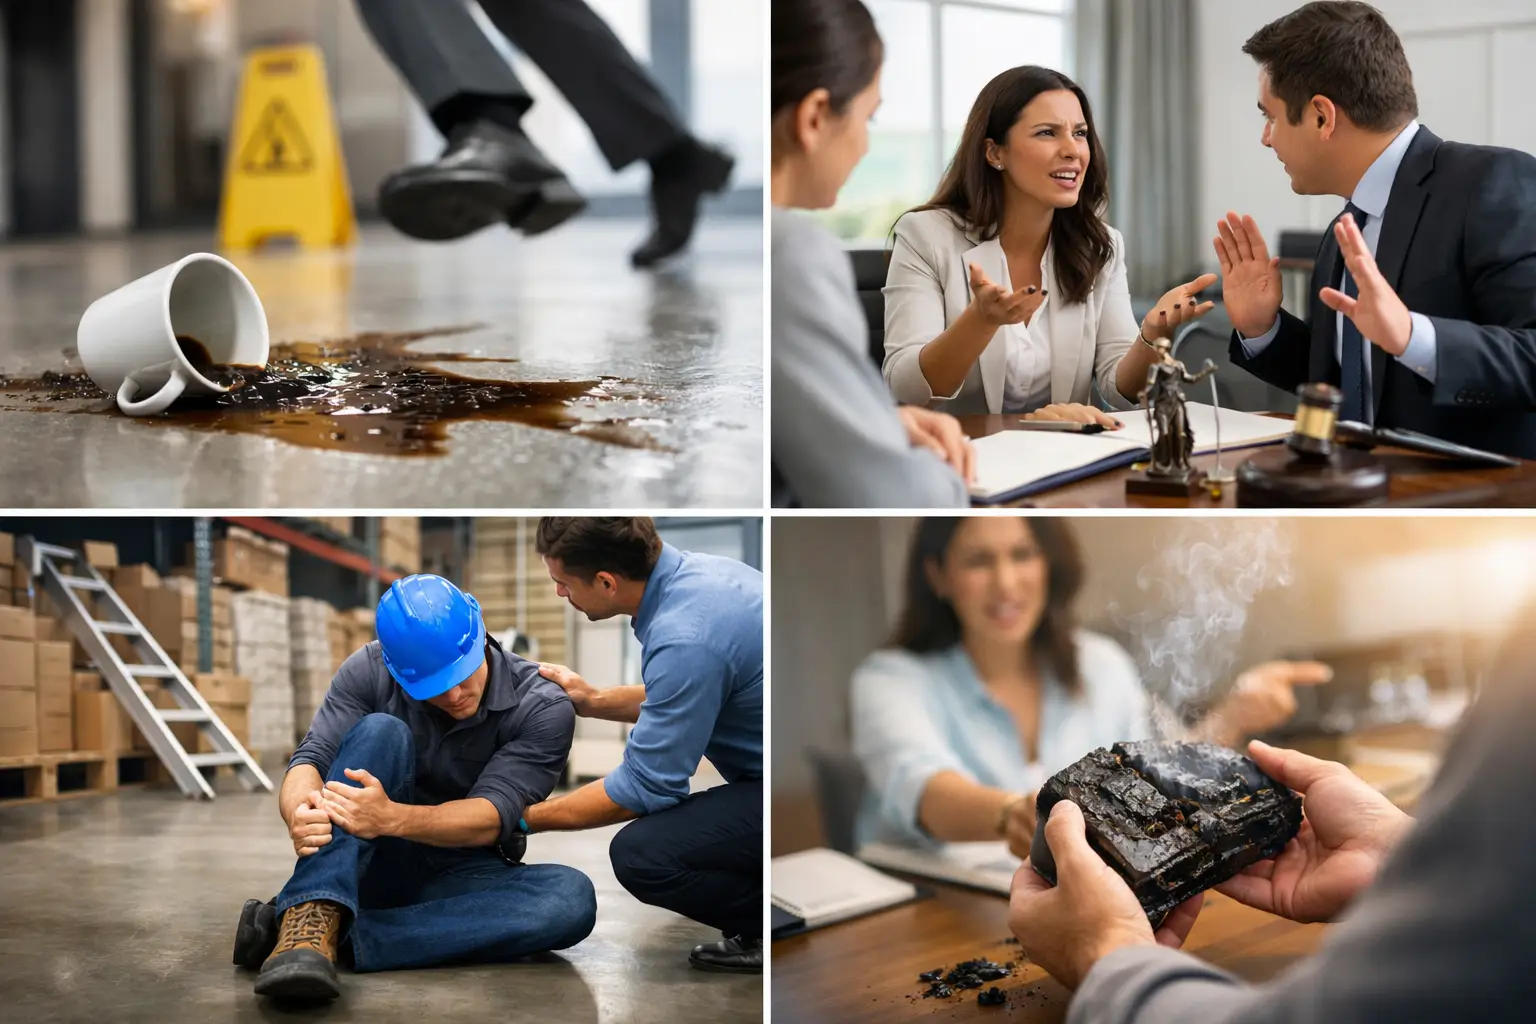
A customer slips on a damp entryway after a foggy Central Coast morning. A technician accidentally damages a client’s custom cabinetry. A social media post triggers an allegation that your business harmed a competitor’s reputation. These business liability claim examples can begin with one ordinary workday, then quickly become expensive distractions from the business you have worked hard to build.
For California business owners, liability protection is not simply a requirement to check off. It is a practical way to protect cash flow, contracts, equipment, and the confidence you have built with customers. The right coverage depends on what you do, where you operate, who enters your property, and the services or products you provide.
Why business liability claims can be complicated
A liability claim starts when someone alleges your business caused an injury, property damage, financial loss, or reputational harm. That allegation may be valid, partially valid, or unfounded. Even when your business did nothing wrong, responding can require legal defense, documentation, and time away from operations.
There is no single policy that covers every type of liability. General liability is often the foundation for claims involving third-party bodily injury, property damage, and certain personal or advertising injuries. But professional mistakes, employee allegations, cyber incidents, and auto accidents usually call for separate coverage. Policy terms, exclusions, deductibles, and limits matter as much as the policy name.
8 business liability claim examples California owners should know
1. A customer is injured on your premises
A customer enters your retail shop, tasting room, office, or restaurant and falls on a recently mopped floor. They suffer a fractured wrist and claim the business failed to post a warning sign or clean up a spill promptly. Medical bills, lost wages, and legal costs can follow.
This is one of the most familiar general liability scenarios. A general liability policy may help pay covered medical expenses, settlements, judgments, and legal defense costs. The outcome can depend on the facts, including maintenance records, security footage, warning signage, and policy conditions.
2. Your work damages a client’s property
A landscaper cracks an irrigation line while installing plants. A cleaning crew damages an expensive stone countertop. An electrician drills into a wall and strikes a water pipe, causing damage to flooring and furnishings.
Claims involving damage to someone else’s property are common for contractors and service businesses. General liability may respond to covered third-party property damage, but there can be important distinctions between accidental damage and the cost to repair defective work itself. A contractor’s policy should be reviewed with the actual scope of work in mind, not just selected because it meets a contract requirement.
3. An advertising dispute leads to a lawsuit
A local business runs an ad that uses an image without proper permission. Another company says your campaign copied its branding or made misleading statements that damaged its reputation. The claim may allege copyright infringement, libel, slander, or misappropriation of advertising ideas.
Certain personal and advertising injury claims may fall under a general liability policy, subject to its wording and exclusions. Intentional conduct, contractual disputes, and intellectual property allegations can be more complicated than they first appear. Careful marketing review and documented permission for photos, testimonials, and creative assets are valuable risk controls.
4. A product causes injury or property damage
A specialty food producer sells a mislabeled item containing an undeclared allergen. A retailer sells a defective outdoor accessory that breaks during normal use. A maker of skin care products faces allegations that a product caused an adverse reaction.
Product liability claims can affect manufacturers, distributors, retailers, and online sellers. General liability policies may include products-completed operations coverage for certain claims of bodily injury or property damage caused by products after sale. Businesses should also consider their supply chain, labeling practices, recalls, product testing, and contractual obligations to vendors.
5. A client says your professional advice caused a loss
A consultant provides guidance that leads a client to make a costly decision. A bookkeeper makes an error in financial records. A design professional delivers plans with an omission that delays a project and creates added expense.
This example highlights a major coverage gap many service businesses overlook. General liability typically does not cover claims arising from professional services or advice. Professional liability, sometimes called errors and omissions coverage, is designed for allegations of negligence, errors, omissions, or failure to deliver professional services as promised. Whether you need it depends on the expertise clients are paying you to provide.
6. A subcontractor’s mistake brings your business into the claim
A general contractor hires a subcontractor whose work leads to an injury at a job site. The injured party names the property owner, general contractor, subcontractor, and project manager in the same lawsuit. Even if another party caused the problem, your business may still need to defend itself.
Construction-related liability can be especially layered. Contracts, additional insured requirements, certificates of insurance, indemnification language, and subcontractor vetting all play a role. Coverage should be aligned with the projects you take on, including residential work, commercial work, coastal properties, renovations, and higher-risk operations.
7. A guest alleges foodborne illness
After a catered event, several attendees report getting sick and claim the food was improperly stored or prepared. A restaurant, caterer, food truck, bakery, or event venue could face demands for medical costs, refunds, and lost income.
Foodborne illness allegations can create immediate reputational pressure as well as a potential liability claim. General liability may help with covered bodily injury claims, but prompt action matters. Preserve records, identify vendors and batch information, document food handling procedures, and notify your insurer according to the policy’s reporting requirements.
8. A hacked system exposes customer information
A small business’s payment system is compromised, exposing customer card data and contact information. The business must notify affected individuals, investigate the breach, restore systems, and respond to potential lawsuits or regulatory inquiries.
This is a liability claim example that usually requires cyber liability coverage rather than general liability alone. Cyber policies may help with expenses such as breach response, notification, credit monitoring, data recovery, and certain legal costs, depending on the policy. For any business that stores customer information, takes payments, or relies on cloud-based systems, cyber protection deserves a direct conversation.
What coverage may help when a claim arises
A thoughtfully built insurance program often begins with commercial general liability, then adds coverage based on your actual exposures. A professional firm may need errors and omissions coverage. A restaurant may need stronger product and food liability considerations. A contractor may need protection tailored to completed operations, subcontractor exposure, and job-site risks. A company with vehicles, employees, or customer data needs to address those risks separately.
An umbrella policy can also provide additional liability limits above certain underlying policies. This can matter when a severe injury or major property loss exceeds the limits of a base policy. It is not a substitute for choosing the right underlying coverage, and it will not fill every exclusion, but it can be a meaningful layer of financial protection for businesses with significant assets or public-facing operations.
Build protection around how your business actually operates
The strongest liability strategy combines insurance with day-to-day risk management. Keep incident reports, maintenance logs, signed contracts, certificates from subcontractors, employee training records, and customer communications organized. These records can help you respond clearly if an allegation is made months later.
It also helps to review your coverage before a lease renewal, major project, new service launch, expansion, or contract signing. A policy purchased when you were a one-person operation may no longer reflect a growing team, a new location, online sales, or larger client commitments.
Central Coast Insurance can help California business owners look beyond a generic policy and identify coverage that reflects the property, people, customers, and work at stake. A short coverage conversation now can make it far easier to keep moving forward when an unexpected claim arrives.