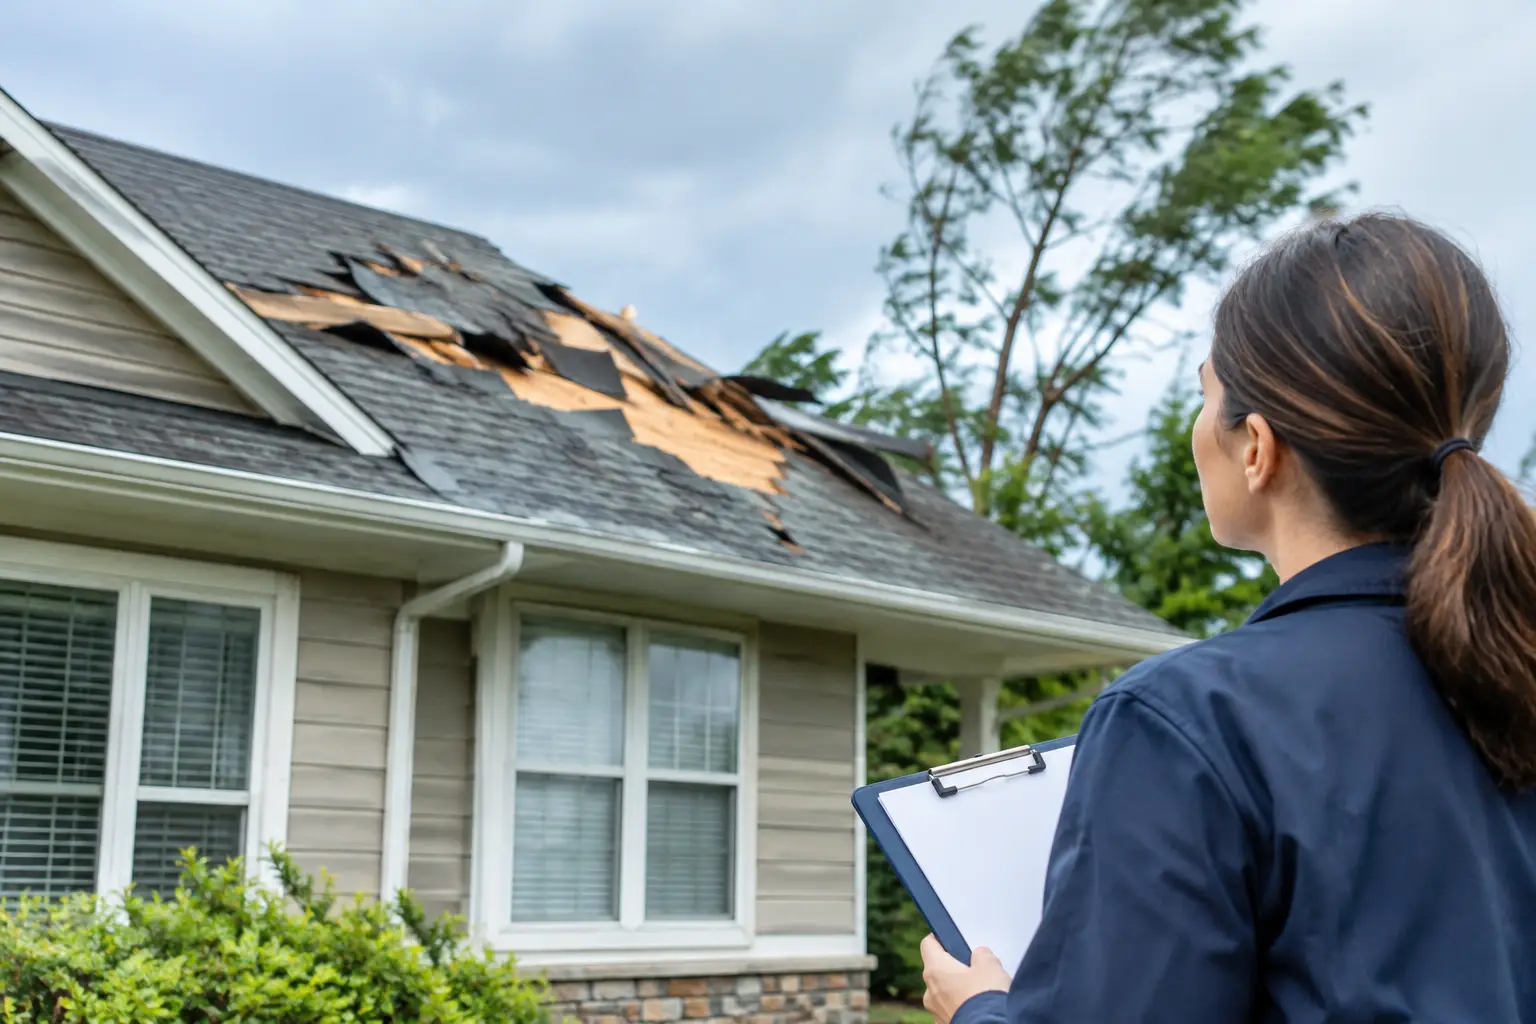
A powerful coastal storm can turn a few hours of wind into missing shingles, fallen fences, broken windows, and water damage inside the home. So, does homeowners insurance cover wind? In many cases, yes. A standard homeowners policy typically covers sudden, accidental wind damage to the home and other covered structures. But the answer depends on the cause of loss, the policy language, your deductible, and whether water entered the property after the wind damage occurred.
For California homeowners, especially those near the coast or in higher-elevation communities, a policy review is one of the best ways to understand what protection is actually in place before the forecast turns serious.
Does Homeowners Insurance Cover Wind Damage to Your Home?
Most homeowners insurance policies include wind as a covered peril. If high winds tear off roof shingles, damage siding, break a window, or blow down a covered structure such as a detached garage, the policy may help pay for repairs, subject to your deductible and coverage limits.
Coverage usually applies to the physical structure of the home under dwelling coverage. It may also extend to detached structures under other structures coverage, personal belongings under personal property coverage, and additional living expenses if a covered wind loss makes the home temporarily unlivable.
The details matter. Insurance is designed for sudden and accidental damage, not gradual wear. A roof that fails because it is old, poorly maintained, or already deteriorated may not be covered simply because wind was present on the day the leak appeared. When a claim involves both weather and maintenance concerns, the insurer will evaluate the specific facts and evidence of damage.
What Wind Damage May Be Covered?
Wind claims look different from one property to the next, but covered losses often include direct damage caused by gusts or windblown debris. A tree limb that falls onto the roof during a storm, for example, may be covered if it damages the home. The cost to repair the roof and interior water damage may also be covered when rain entered through an opening created by the wind event.
Common examples include:
- Shingles, tiles, flashing, siding, gutters, or solar panels damaged by high winds
- A fence, shed, or detached garage damaged by a windstorm, subject to its separate coverage limit
- Windows or doors broken by windblown debris
- Personal belongings damaged when wind creates an opening that allows rain into the home
- Temporary lodging and certain extra living costs when a covered loss makes the home unsafe to occupy
Coverage for landscaping, outdoor furniture, docks, gates, and retaining walls can be more limited. Trees and shrubs may have limited coverage, while the cost to remove a fallen tree is often covered only when it damages a covered structure or blocks a driveway. These are the kinds of policy details worth clarifying before a loss.
Water Damage After Wind Damage
One of the most misunderstood parts of a wind claim is the role of water. Homeowners insurance generally does not cover flood damage, meaning water that rises or flows over normally dry land. A separate flood policy is needed for that exposure.
However, rainwater that enters through a roof, window, or wall opening caused directly by covered wind damage may be covered. The difference is how the water got inside. If wind lifts part of a roof and rain damages ceilings and flooring, that may be a covered wind-related loss. If storm surge, overflowing creeks, or surface water enters the property, that is generally a flood issue instead.
When Wind Damage May Not Be Covered
Every policy has exclusions and conditions. Wind damage may be denied or limited when the loss is tied primarily to neglect, deterioration, faulty construction, or a pre-existing condition. Insurers expect homeowners to maintain roofs, secure loose exterior materials, trim hazardous limbs where practical, and address known leaks.
Damage from earth movement is also different from wind damage. If a windstorm contributes to a mudslide, landslide, or settling issue, homeowners insurance may not cover the resulting damage. California property owners should be particularly careful not to assume one weather event means every type of damage is covered.
Some policies may have special deductibles or restrictions for named storms, windstorms, or homes in higher-risk areas. These provisions are more common in certain parts of the country, but coverage forms and deductibles vary by carrier and property. Coastal homeowners should not rely on assumptions based on a neighbor's policy or a general online answer.
How Deductibles Affect a Wind Claim
A deductible is the portion of a covered loss you pay before insurance contributes. If a storm causes $12,000 in covered roof and interior damage and your deductible is $2,500, the insurer may pay up to $9,500, assuming the claim is approved and the damage falls within applicable limits.
Many homeowners have a flat-dollar deductible, but some policies use percentage deductibles for certain weather losses. A 1% or 2% deductible can be significant on a higher-value California home because it is calculated from the insured value of the dwelling, not the size of the repair bill.
It is also worth considering whether filing a small claim makes financial sense. If repair costs are only slightly above your deductible, paying out of pocket may be the more practical choice. For major damage, however, prompt reporting helps start the inspection and recovery process.
What to Do After a Windstorm
Safety comes first. Stay away from downed power lines, unstable trees, broken glass, and damaged roof areas. If the home has a compromised roof or opening, take reasonable temporary steps to prevent further damage, such as covering the opening with a tarp when it is safe to do so. Keep receipts for emergency mitigation work.
Next, document the damage before repairs begin. Take clear photos and videos of the exterior, interior, damaged belongings, and any debris that appears connected to the event. Make a written list of what happened, including the approximate time of the storm and when you noticed the damage.
Then report the claim to your insurer or agent as soon as possible. Do not discard damaged materials until the claims process allows it, unless they present a safety hazard. Avoid signing a repair contract that assigns your insurance benefits without understanding the terms. A qualified contractor can help assess damage, but your insurer determines coverage under the policy.
Preparing Your California Home for High Winds
Wind preparedness can reduce the chance of a claim and help protect the people inside your home. Start with the roof. Replace missing shingles or tiles, secure loose flashing, clean gutters, and address leaks before a storm exposes them. Check fences, gates, sheds, patio covers, and outdoor equipment for loose components that can become airborne.
Trees deserve attention too. Have dead or overhanging branches evaluated, particularly those near the roof, service lines, or vehicles. During a wind advisory, bring in or secure patio furniture, umbrellas, planters, and other outdoor items. If you live near the coast, corrosion from salt air can weaken fasteners and exterior materials over time, making regular inspections especially valuable.
Your insurance protection should be part of that preparation. Confirm that your dwelling limit reflects what it would cost to rebuild locally, not simply what you paid for the home. Review coverage for detached structures, personal property, temporary housing, and valuable items that may need scheduled coverage.
A Policy Review Brings Clarity Before the Next Storm
Wind coverage is often included in homeowners insurance, but the most useful answer comes from reading the policy built for your address, home, and risk profile. The age and condition of the roof, proximity to trees, coastal exposure, deductible selection, and rebuilding costs can all shape how well a policy responds.
Central Coast Insurance can help California homeowners look beyond the declaration page and understand where coverage is strong, where limits may apply, and what questions to ask. A thoughtful review before storm season can replace uncertainty with a plan that protects the home and the life built around it.